Federal flood insurance (NFIP) is authorized only through Dec 11, 2026 FEMA, updated Sep 28, 2026
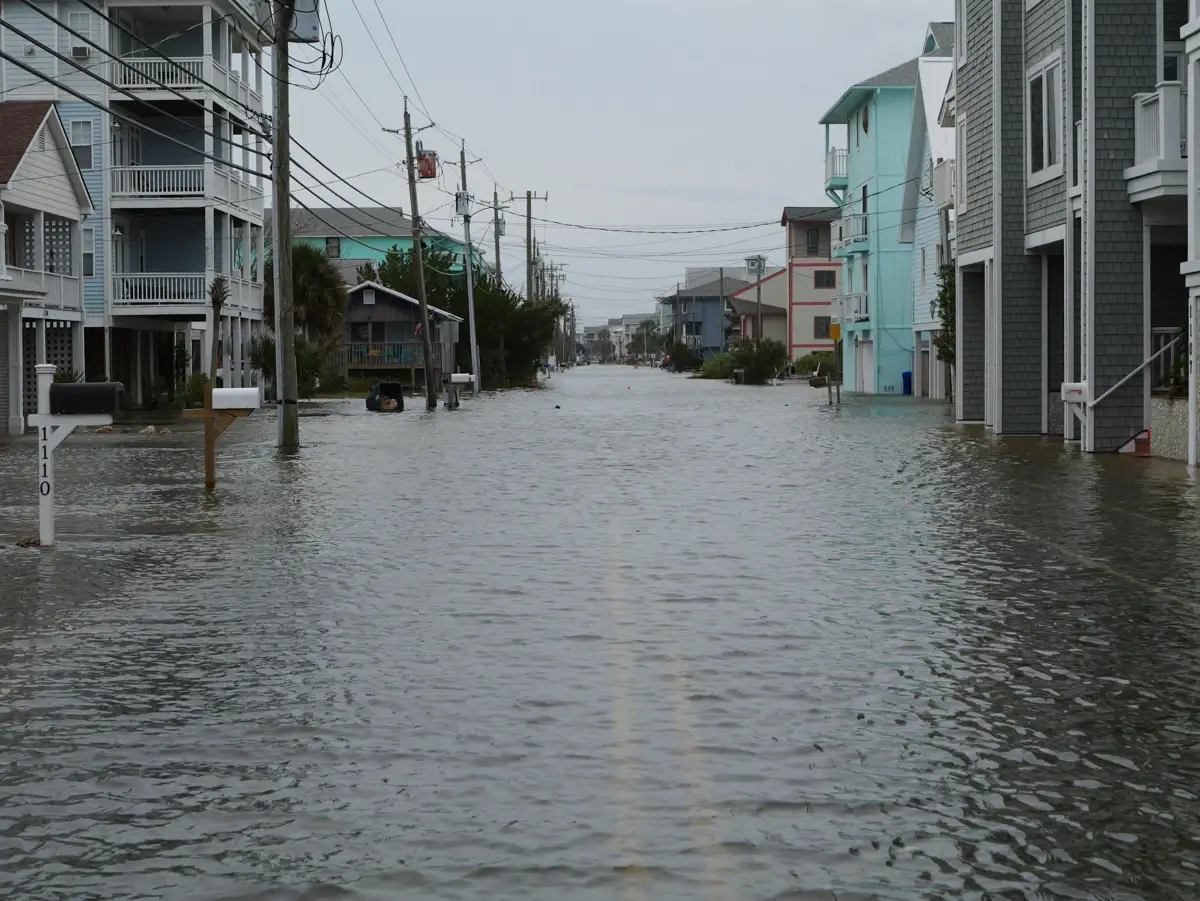
A residential street under floodwater between raised houses.

Free check · flood, hurricane, tornado, wildfire, quake

What will this house cost you when the water comes?

Type an address. See its flood zone, flood claims nearby, FEMA ratings for 18 hazards and live warnings, free. Then decide if you want the full report.

Which describes you?
  • Free, no account
  • Full refund if we can't build it
  • Every number has a source

No address handy? Get the field guides, from $19 →

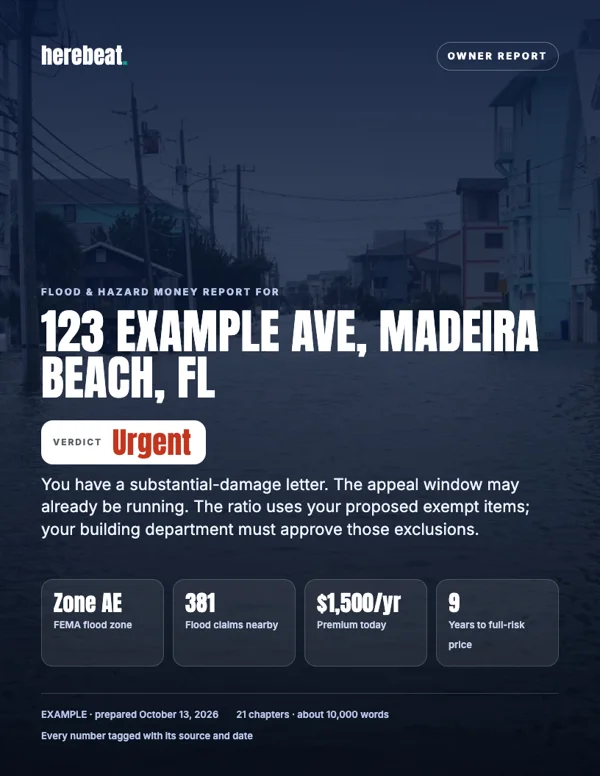
Owner Report sample cover (example data)
Full report$29 one-time · 21 chapters + PDF
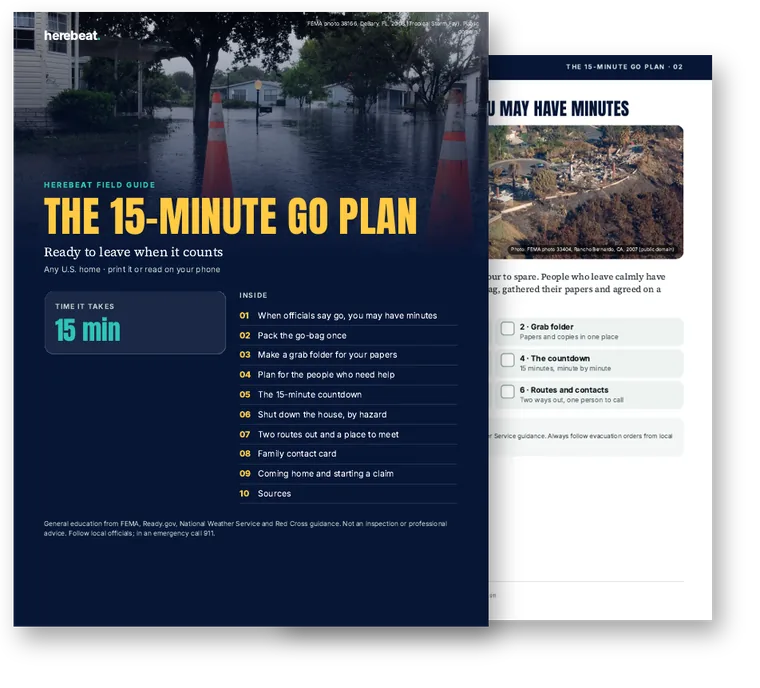
Field guide cover and sample page
Field guides$19 each · both $29

Photo: Richard R / Unsplash

$0to see your flood zone and verdict
21 chaptersOwner Report, with a PDF
18 hazardsrated for your neighborhood (FEMA)
Full refundif we can't build it, no forms

Three ways in.

Free

Free address check

Flood zone, flood claims nearby, the premium trend, FEMA ratings for 18 hazards and live warnings for one address.

Check an address
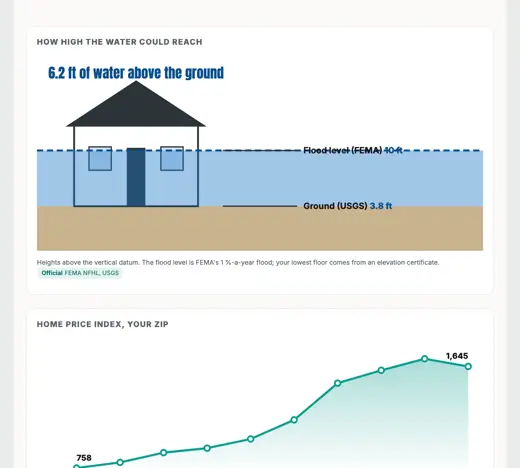
Owner Report sample page (example data)
$29 one-time

The full report

Owner Report (21 chapters) or Buyer Check (16), written for your address after the free check, with a PDF. Add the 3 DIY kits for $19 more.

See what's in it
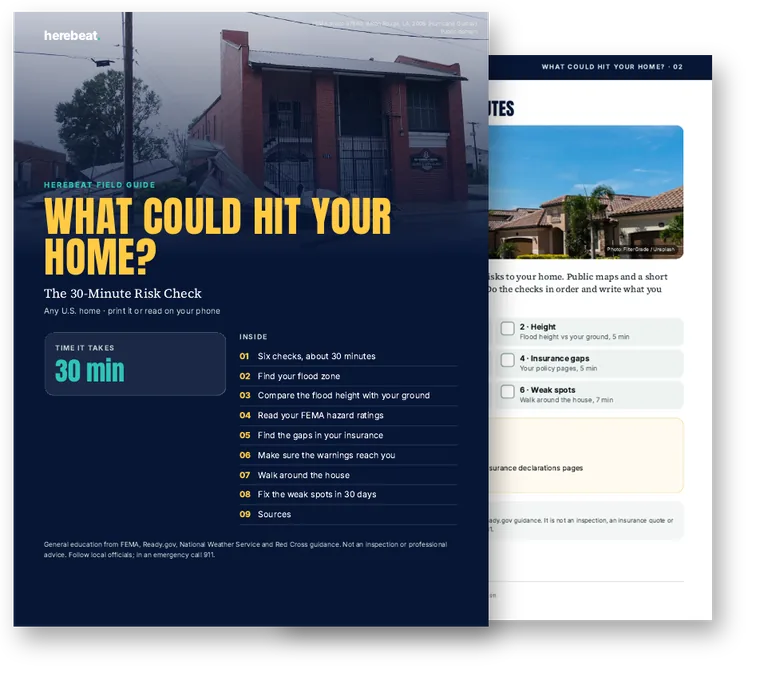
Field guide cover and sample page
$19 · both $29

Field guides

Two illustrated PDFs for any U.S. home: the 30-minute risk check and the 15-minute go plan. No address needed.

Get the guides

Field guides · any U.S. home · no address needed

Be ready before the warning.

Two illustrated PDF guides built from FEMA, Ready.gov and National Weather Service guidance. Print them or keep them on your phone.

What Could Hit Your Home?: cover and a sample page
The 30-Minute Risk Check

What Could Hit Your Home?

Read your flood map, your FEMA hazard ratings and your insurance gaps in one sitting, then fix the weak spots in 30 days.

  • How to read the FEMA flood map for any address
  • The 18 hazards FEMA rates, and how to read yours
  • What homeowners insurance usually does not cover
  • A walk-around checklist and a 30-day plan
The 15-Minute Go Plan: cover and a sample page
Ready to leave when it counts

The 15-Minute Go Plan

Pack once, plan once, and walk out the door in 15 minutes when officials say go, with the papers you will need after.

  • Go-bag and grab-folder lists you can tick off
  • A minute-by-minute 15-minute countdown
  • House shutdown steps for flood, hurricane, wildfire
  • Routes, meeting places and a family contact card
Both guides: $29$38 if bought one by one.

Not only water

Flood, hurricane, tornado, wildfire, quake.

Every report rates your neighborhood for 18 hazards with FEMA's National Risk Index, shows the live official warnings for your spot, and turns the serious ones into steps for this house. Flood gets the full money analysis.

A flooded residential street with orange traffic cones.FloodDeBary, FL, 2008. Photo: FEMA (public domain)
Full money analysis

Flood

  • Your FEMA flood zone and flood height at the exact spot
  • Flood claims in your neighborhood, year by year
  • Your flood premium, year by year, to full price
  • The 50 % rule with your repair numbers, ICC and grants
Check my address: free
A house with storm damage after a hurricane.Hurricane & windBaton Rouge, LA, after Hurricane Gustav, 2008. Photo: FEMA (public domain)
Rated for your neighborhood

Hurricane & wind

  • FEMA's hurricane and strong-wind ratings for your neighborhood
  • Live official hurricane and wind warnings for your spot
  • A storm-season playbook for this house
  • Questions to ask your insurer about wind coverage and deductibles
Check my address: free
A residential neighborhood damaged by a tornado.TornadoChapman, KS, after an F-3 tornado, 2008. Photo: FEMA (public domain)
Rated for your neighborhood

Tornado

  • FEMA's tornado and hail ratings for your neighborhood
  • Live official tornado warnings for your spot
  • Where to shelter and what to prepare, for this house
  • What to check in your homeowners policy
Check my address: free
An aerial view of homes destroyed by a wildfire.WildfireRancho Bernardo, CA, after the Witch Creek fire, 2007. Photo: FEMA (public domain)
Rated for your neighborhood

Wildfire

  • FEMA's wildfire rating for your neighborhood
  • Live official fire-weather warnings for your spot
  • Steps that lower the risk around the house
  • Questions to ask if your insurer raises rates or drops you
Check my address: free
A building with a cracked foundation and a red safety tag on the door.EarthquakeNapa, CA, after the 2014 earthquake. Photo: FEMA (public domain)
Rated for your neighborhood

Earthquake

  • FEMA's earthquake and landslide ratings for your neighborhood
  • Why most home policies leave out earthquakes, and what to ask
  • Basic retrofit questions for an inspector
  • Live official alerts in the Herebeat app
Check my address: free

Swipe or tap the arrows. Ratings describe your neighborhood, not one house.

Coastal floodingRiver & rain floodingHurricaneTornadoStrong windHailLightningWildfireEarthquakeLandslideHeat waveCold waveWinter weatherIce stormDroughtTsunamiAvalancheVolcanic activity

Not just mansions

Ordinary houses. Same rules.

A bungalow, a porch house, a farmhouse, a house on stilts. If it sits in a flood zone, the same 50 % rule, the same yearly premium increases and the same paperwork apply. The report works it out for yours.

A gray bungalow with a porch and palm trees in Fort Myers, Florida.
OwnerIs my repair over the 50 % line?
A modest house with a front porch and an American flag.
OwnerWhere is my premium heading?
A white two-story farmhouse with a wraparound porch.
BuyerWhere are flood insurance costs heading?
A light blue house raised on stilts by the water.
BuyerShould I walk away or negotiate?

Photos: Sieuwert Otterloo, Jason Gooljar, Jacob McGowin, Cameron J. / Unsplash. Illustrative, not report subjects.

The math

What one flood can cost you.

What's at stake

Raising a house after a substantial-damage findingEstimates a Madeira Beach homeowner reported, WFTS Tampa Bay 28
$175K–$400K
Flood premium rise, every year, until full pricePrimary home; 3 years at the cap is +64 %. Second homes up to 25 %. 42 U.S.C. 4015(e)
Up to 18 %
ICC payout toward raising or rebuildingOnly for NFIP policyholders found substantially damaged. 44 CFR Part 61, App. A(1)
Up to $30,000
Substantial-damage findings reversed on appealSingle-family homes that appealed, unincorporated Pinellas County, FL, Bay News 9, Oct 31, 2025
About 70 %

What your report works out

Your 50 % ratio, the line and the gapFrom your repair estimate and building value, with the scenarios that move you across the line
Your number
Your flood premium, year by yearFrom today's area price to the full-risk price, at the legal cap
Year by year
ICC and grants you may qualify forEach program with its status (open, closed, unknown) and the date we checked
With dates
What to do, and whenDocuments to gather, who to call, deadlines, a 90-day plan
90 days

A $29 report that changes one of these numbers pays for itself many times over.

Photo: DeBary, FL, after Tropical Storm Fay, 2008. FEMA (public domain).

Milford, Connecticut, after Hurricane Sandy: a house raised on pilings stands with little damage beside a house that was not raised and collapsed.
Owner ReportEXAMPLE

11The 50 % rule check

Urgent
Repair estimate Your input$95,000
Building value$143,537
Over the line by$23,232

Photo: Milford, CT, after Hurricane Sandy, 2012. The raised house stood; the one beside it did not. FEMA (public domain). Report page: example numbers.

For the house you own

The Owner Report

  • The 50 % rule, with your numbers.Your ratio, the line, the gap, and the scenarios that move you across it. What counts, what doesn't, who decides.
  • Your premium path, and how to slow it.Year by year to the full price, plus the elevation certificate, mitigation and your town's discount class.
  • Grants, ICC and a 90-day plan.Each program with its status and date, documents to gather, and a storm-season playbook for this house.
$29one-time price · 21 chapters + PDF
Start with the free check →
50 % Rule Appeal Kit: included in the report + kits comboWhen your own numbers put you at 40 % or more of the building's value, the combo adds the Appeal Kit too: the evidence that can lower your ratio, a pre-filled appeal letter, the deadline and where to send it. Education only; nobody can promise an outcome.
A gray two-story house with a front porch decorated with red, white and blue bunting.
Buyer CheckEXAMPLE

1Verdict

Go with conditions
Flood insurance onlyPer month
Year 1$473–$506
Year 3$579–$613
Year 5$636–$669

EXAMPLE: tax and local fees not included.

Photo: Breno Burnett / Unsplash. Report page: example numbers, not a real listing.

For a house you're about to buy

The Buyer Check

  • A clear verdict, by rules you can read.Go, Go with conditions, or Walk away / renegotiate, with the red flags that decided it.
  • Your flood insurance costs, 5 years out.Flood insurance only for years 1, 2, 3 and 5, against the monthly budget you set. Property tax, homeowners insurance, local fees and the mortgage are not included.
  • What to demand before you sign.Documents only the seller can get, and questions for the seller, insurer, lender and town.
$29one-time price · 16 chapters + PDF
Start with the free check →

Do-it-yourself kits

The next steps, done for you.

Illustrated guides, scripts, letters and spreadsheets, built from your free check for your address. Buy them on their own, or add all of them to your report.
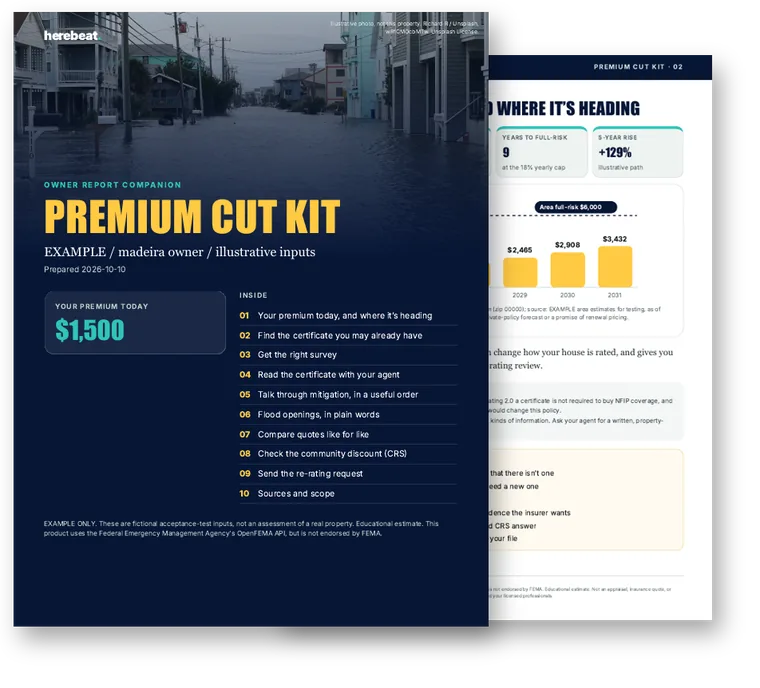
Premium Cut Kit: sample pages with example data
Owners and buyers

Premium Cut Kit $15

Find or order an elevation certificate, read it with your agent, compare quotes like for like, and send a re-rating request. Illustrated guide + editable Word letter.
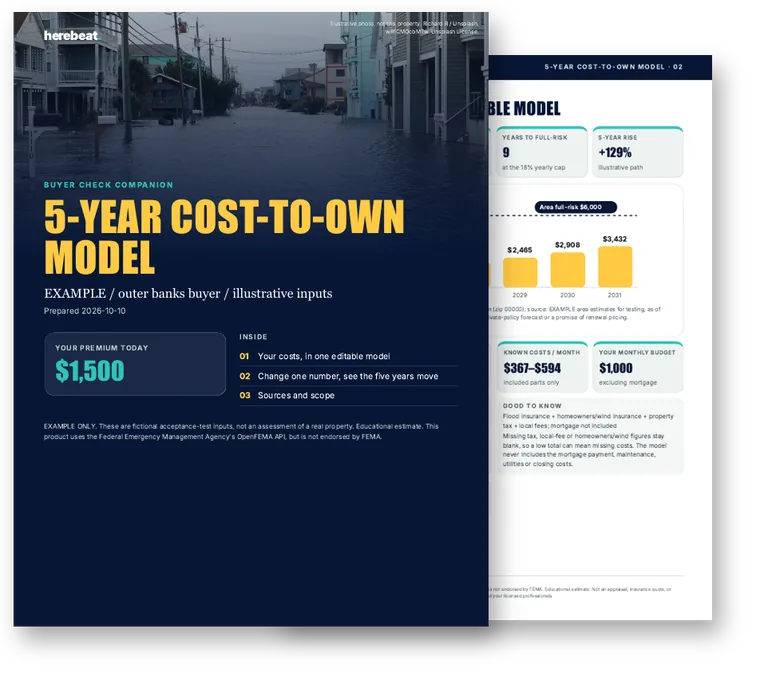
5-Year Cost-to-Own Model: sample pages with example data
Owners and buyers

5-Year Cost-to-Own Model $12

Premium path, taxes and local fees in an Excel model with live formulas. Change one number and watch five years move. Spreadsheet + illustrated guide.
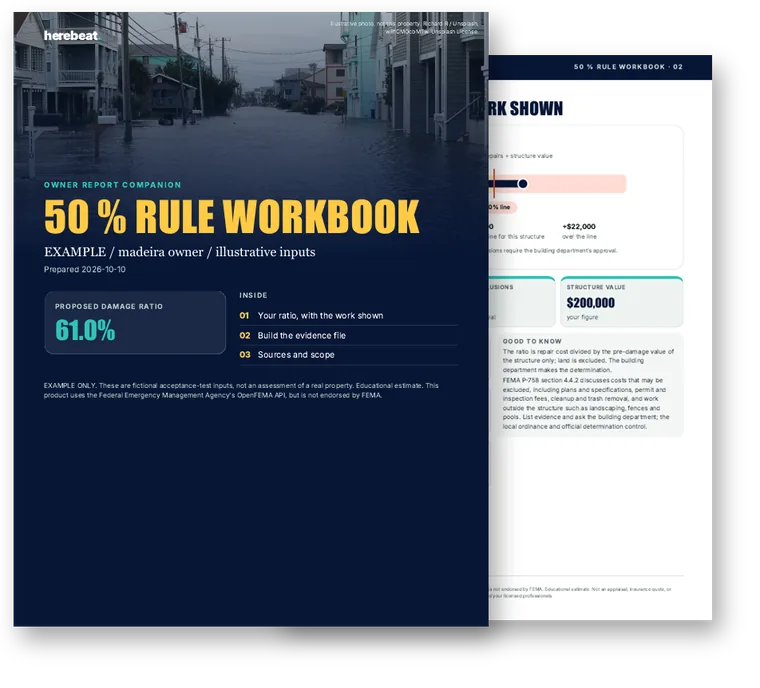
50 % Rule Workbook: sample pages with example data
Owners

50 % Rule Workbook $12

Your repair ratio with the work shown: itemize repairs, mark what may not count, try an independent value, build the evidence file. Spreadsheet + guide.
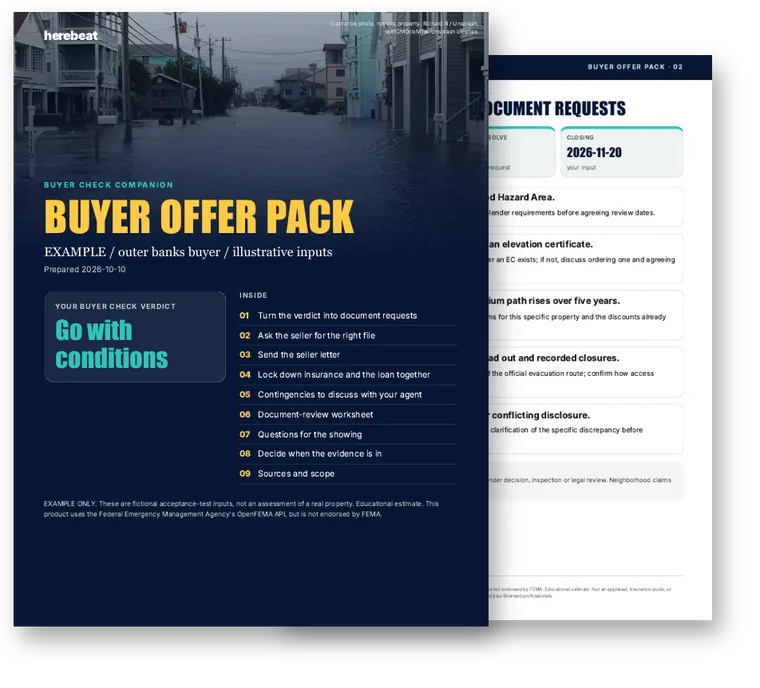
Buyer Offer Pack: sample pages with example data
Buyers

Buyer Offer Pack $19

Your verdict turned into a seller document request, a contingency checklist for your agent and questions for the showing. Guide + editable letters.

Report + all 3 kits that fit your house: only $19 more.The kits alone are $39 to $46 one by one. All 3 kits without the report: $29.
Start with the free check →

Sample pages use fictional example data. Kits are built for your address after the free check; any kit we can't build is refunded.

What's inside

Every chapter, for one address.

Chapters 1–4

The verdict and your house

The answer first, then the facts it rests on.

  1. 1Summary & verdict
  2. 2Your property
  3. 3Flood exposure
  4. 4Neighborhood flood history
Chapters 5–7

What reaches this spot

Storms, tides and other hazards, from measured data.

  1. 5Storms that reached here
  2. 6Sea level & high tides
  3. 7Other hazards
Chapters 8–10

Your insurance money

Where the premium is going and how to slow it.

  1. 8Insurance: now & next
  2. 9Ways to lower your premium
  3. 10Value vs. cost of owning
Chapters 11–14

The 50 % rule and help

Your ratio, your options, and who pays.

  1. 11The 50 % rule check
  2. 12Your options compared
  3. 13Grants & programs
  4. 14Who pays locally
Chapters 15–18

Your plan

What to do, in order, with dates.

  1. 15Your 90-day plan
  2. 16Documents to gather
  3. 17Storm-season playbook for this house
  4. 18Questions to ask
Chapters 19–21

Plain and checkable

Words explained, gaps listed, sources dated.

  1. 19Plain-English glossary
  2. 20What we couldn't check
  3. 21Sources & dates

Free before you pay: your verdict and key numbers for this address. The full report is written after payment, for your address only: about 7,000–10,000 words (Owner) or 5,500–8,000 (Buyer), on screen and as a PDF.

How it works

Five steps. Pay at the last one.

  1. Type the addressThe free check shows the flood zone, claims nearby and live warnings.
  2. Confirm the pinFlood-zone lines can split a block, so we check the exact spot.
  3. Answer a few questionsAbout the house and your money. About 3 minutes.
  4. See your free previewConfirm your email; your verdict and key numbers appear.
  5. Get the full reportPay only if it's useful. On screen, plus a PDF by email.
A quiet Florida street lined with houses and palm trees.

Why we built this

"What about my house?"

We make Mansions Destroyed on YouTube: one real place per episode, following the water, the money and the decisions, with every number from public records. Viewers keep asking about their own house.

So we built the report the videos can't be: the same public data, run for one address, with your own numbers. And Herebeat, our iPhone app, keeps watching it with official alerts.

Mansions Destroyed@MansionsDestroyed on YouTube
142,000+views
19episodes
1,090subscribers

Channel figures from YouTube, Oct 10, 2026. Channel started Sep 18, 2026.

  • FEMA flood maps
  • OpenFEMA claims & policies
  • USGS
  • National Weather Service
  • USFWS
  • FHFA
  • U.S. Census

This product uses the Federal Emergency Management Agency's OpenFEMA API, but is not endorsed by FEMA. Photo: FilterGrade / Unsplash.

The guarantee

Full refund.
No forms.

If we can't build the report for your address, or it fails our accuracy checks, you get your money back automatically. Think it's wrong? Write to reports@herebeat.app within 14 days.

Questions

Before you start.

Is this an appraisal?

No. It's an educational estimate built from public government data and your inputs. It isn't an appraisal, an insurance quote, a flood determination, or legal, financial or lending advice. Your building department decides substantial damage, insurers set premiums, and lenders decide loans.

Where does the data come from?

FEMA's flood maps, OpenFEMA flood claims and policies, the FEMA Community Status Book, the U.S. Fish and Wildlife Service, USGS, the National Weather Service, the FHFA house price index and the U.S. Census, plus state rules and grant programs we track with their dates. Every report lists each source and date, and what we couldn't check.

Does it work for inland homes and condos?

Yes. Inland reports swap the sea-level and shoreline chapters for rivers, heavy rain and drainage. For a condo unit, the 50 % rule is decided for the whole building, so the report explains the association's master policy, your unit policy and special assessments instead.

How long does it take?

The free check appears after you confirm the pin. Your free preview follows a few minutes after you confirm your email. The full report is written after payment and takes several minutes more; we email you the link and the PDF.

What if I'm not on the coast?

It works for any U.S. address: flood zone, neighborhood claims, premiums, your town's flood rules and live warnings. Some chapters, like shoreline and local costs, go deepest in Florida, North Carolina, South Carolina and New Jersey for now; the report says plainly what it couldn't check for your address.

Can I use it with my agent or insurer?

Yes. Share the PDF. It lists the documents and questions to bring them, and every figure shows where it came from so they can check it.

Refunds?

If we can't build the report for your address, or it fails our checks, we refund you automatically. Otherwise write to reports@herebeat.app within 14 days. Refund policy.

Privacy?

We use your address, answers and email only to build and deliver your report. We don't sell your data, and the reports never describe the people who live in an area. Privacy policy.

Is my house's own claim history included?

No. FEMA publishes flood claims only by area, not by house. The owner can ask FEMA for the property's NFIP loss history; if you're buying, ask the seller for it as a condition of your offer. The report explains how.

Herebeat for iPhone

Then keep watching it.

The report tells you where the house stands today. The Herebeat app tells you when that changes: official alerts, hurricane cones, storm outlooks, earthquakes, wildfires and water levels for your places, each with the agency that issued it and when.

Free download, subscription required: $7.99/mo or $39.99/yr, billed by the App Store. New subscribers pay $4.99 for the first month or $24.99 for the first year. Not an emergency alert system.
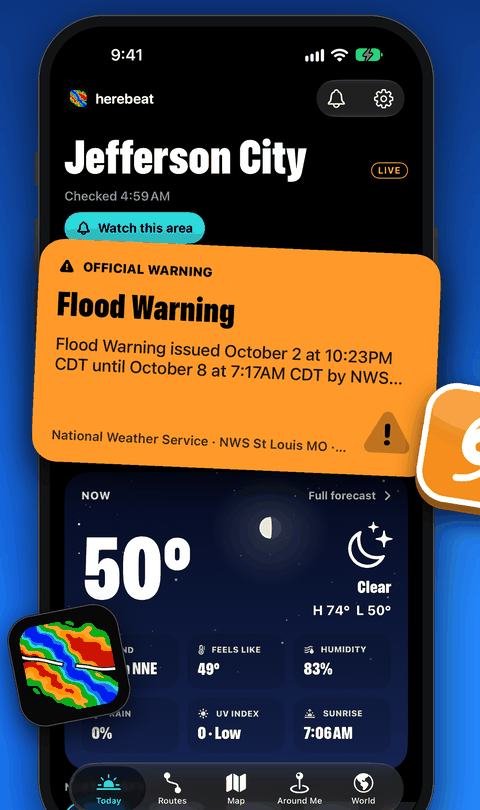
The Herebeat Today screen for Jefferson City, Missouri, with an official National Weather Service Flood Warning card.

Check your address. Free.

Which describes you?

Photo: Cameron J. / Unsplash

Check my address: free